Platinum’s use in a wide range of end-markets sets it up well to recover if the current macro volatility eases
9 October 2026
Platinum’s fundamentals have been overshadowed by macroeconomic factors in 2026. We expect the uncertain external environment to remain a foremost investor consideration in the short term; however, the pullback in platinum prices during 2026 offers an opportunity to build exposure. An important characteristic of platinum is how its diverse end-use consumption helps insulate it from demand shocks. China is illustrative of this as platinum’s 2026 demand narrative starkly differs from 2025 despite net platinum imports recording little change between the years. Platinum’s demonstrable utility reinforces conviction in our medium-term demand outlook and platinum’s investment case beyond the currently unsupportive macro backdrop.
The Fed hiked interest rates by 25 bps in September, and there is a >80% probability of a second hike in December 2026 (after the US mid-terms). Inflation-led interest rate pressure is coinciding with rising real yields (Fig. 3) which appear as likely short-term price headwinds. The 20% YTD price decline (Fig. 4) could be an attractive entry point for platinum as macroeconomic factors overshadow several underappreciated fundamental narratives.
Figure. 1 China’s cumulative Pt imports in 2026 are edging towards the upper bound of historic imports since 2015
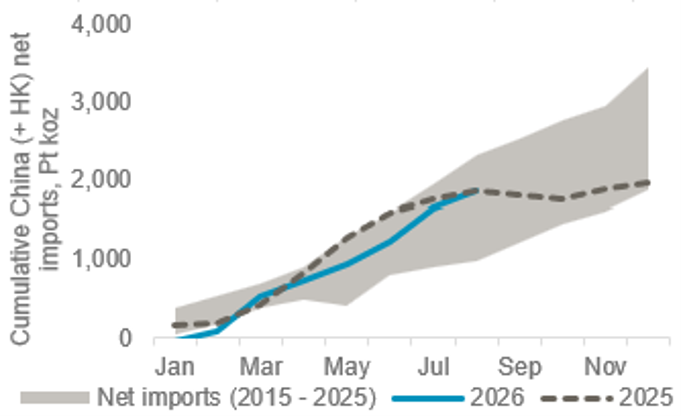
Figure. 2 Platinum demand is well diversified, supporting our conviction in long-term resilience
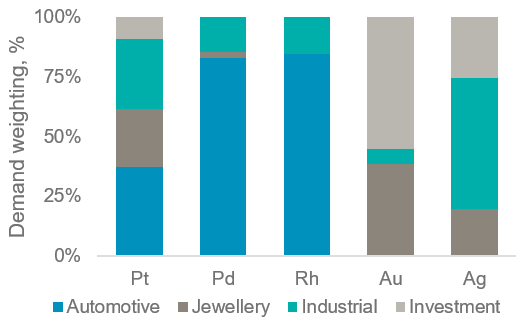
Platinum has the most diversified mix of demand amongst PGMs and the wider precious metals complex of gold and silver (Fig. 2). China, the largest single platinum user, shows how a diverse base of end-markets can insulate demand. The 2025 narrative of jewellery’s resurgence and bar and coin growth (Fig. 5) has reversed in 2026. Jewellery due to higher prices and bar and coin due to the drop in prices from Feb’26. China’s catalysed vehicle production has also declined by >10% YTD (Fig. 6). Despite these headwinds, China’s YTD net platinum imports (incl. Hong Kong) reached 1.85 Moz by August and are matching the 2025 run rate (Fig. 1). While domestic recycling is expected to decline by 56 koz in 2026, demand growth from GFEX warehouse stocks (Fig. 7, ~150 koz) and AI applications (glass, electronics and crucibles) is supporting China’s platinum import demand.
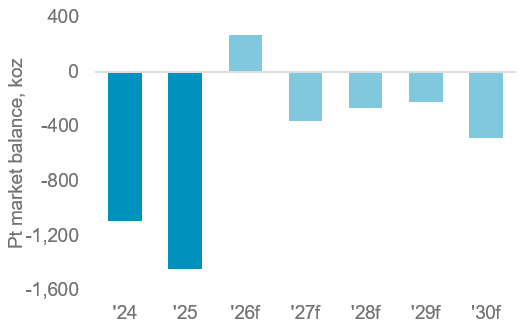
Reflecting on China’s import stability in response to meaningful market shifts offers confidence in platinum’s resilient demand outlook beyond the current macroeconomic environment. Accordingly, we expect platinum markets to revert to a deficit from 2027f following a projected 265 koz surplus in 2026f.
Platinum’s attraction as an investment asset arises from:
- WPIC research indicates that the platinum market entered a period of sustained supply deficits from 2023 to 2025 which depleted above-ground stocks
- Although higher platinum prices have supported increased recycling supply, total supply remains challenged
- Platinum is a critical mineral in the global energy transition with a key role in the hydrogen economy, as well as being an increasingly key input in semiconductor production and AI datacentres
- The platinum price remains historically undervalued and significantly below the price of gold
Figure 3: Alongside rising inflation due to the Iran war, real yields have risen on fiscal and Fed independence concerns
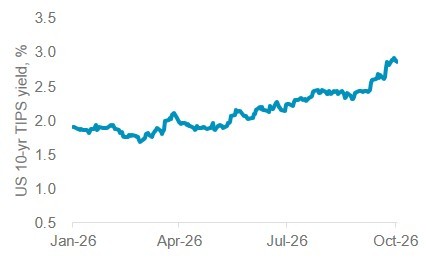
Figure 4: Rising yields have weighed on non-yielding assets with precious metals prices declining during 2026
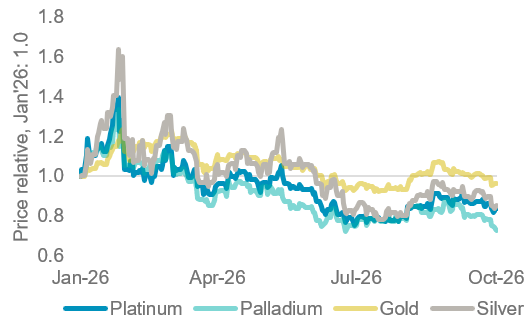
Figure 5: After strong growth in 2025, China’s platinum jewellery and bar & coin* investment demand are expected to decline in 2026f
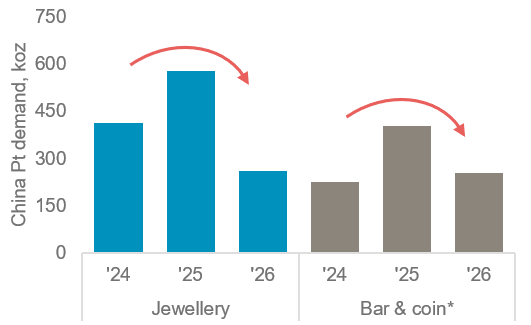
Figure 6: China’s YTD passenger and commercial vehicle production has declined 14% and 1% respectively which supports forecasts a -9% less platinum demand in 2026f
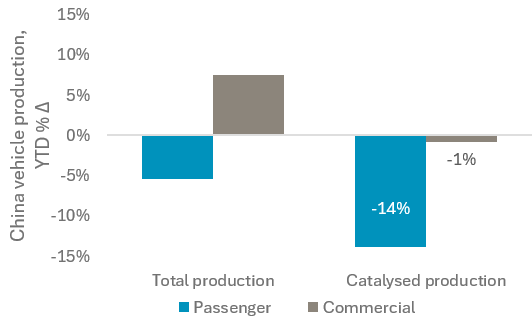
Figure 7: The launch of GFEX platinum futures and forward contracts in 2025 has underpinned the accumulation of warehouse exchange stocks
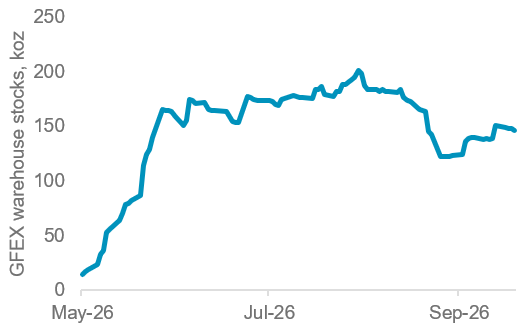
Figure 8: Platinum markets are expected to return to deficits from ’27f following the significant H1’26 investment outflows that underpin a projected FY surplus
IMPORTANT NOTICE AND DISCLAIMER: This publication is general and solely for educational purposes. The publisher, The World Platinum Investment Council, has been formed by the world’s leading platinum producers to develop the market for platinum investment demand. Its mission is to stimulate investor demand for physical platinum through both actionable insights and targeted development: providing investors with the information to support informed decisions regarding platinum; working with financial institutions and market participants to develop products and channels that investors need.
This publication is not, and should not be construed to be, an offer to sell or a solicitation of an offer to buy any security. With this publication, the publisher does not intend to transmit any order for, arrange for, advise on, act as agent in relation to, or otherwise facilitate any transaction involving securities or commodities regardless of whether such are otherwise referenced in it. This publication is not intended to provide tax, legal, or investment advice and nothing in it should be construed as a recommendation to buy, sell, or hold any investment or security or to engage in any investment strategy or transaction. The publisher is not, and does not purport to be, a broker-dealer, a registered investment advisor, or otherwise registered under the laws of the United States or the United Kingdom, including under the Financial Services and Markets Act 2000 or Senior Managers and Certifications Regime or by the Financial Conduct Authority.
This publication is not, and should not be construed to be, personalized investment advice directed to or appropriate for any particular investor. Any investment should be made only after consulting a professional investment advisor. You are solely responsible for determining whether any investment, investment strategy, security or related transaction is appropriate for you based on your investment objectives, financial circumstances and risk tolerance. You should consult your business, legal, tax or accounting advisors regarding your specific business, legal or tax situation or circumstances.
The information on which this publication is based is believed to be reliable. Nevertheless, the publisher cannot guarantee the accuracy or completeness of the information. This publication contains forward-looking statements, including statements regarding expected continual growth of the industry. The publisher notes that statements contained in the publication that look forward in time, which include everything other than historical information, involve risks and uncertainties that may affect actual results. The logos, services marks and trademarks of the World Platinum Investment Council are owned exclusively by it. All other trademarks used in this publication are the property of their respective trademark holders. The publisher is not affiliated, connected, or associated with, and is not sponsored, approved, or originated by, the trademark holders unless otherwise stated. No claim is made by the publisher to any rights in any third-party trademarks
WPIC Research MiFID II Status
The World Platinum Investment Council -WPIC- has undertaken an internal and external review of its content and services for MiFID II. As a result, WPIC highlights the following to the recipients of its research services, and their Compliance/Legal departments:
WPIC research content falls clearly within the Minor Non-Monetary Benefit Category and can continue to be consumed by all asset managers free of charge. WPIC research can be freely shared across investment organisations.
- WPIC does not conduct any financial instrument execution business. WPIC does not have any market making, sales trading, trading or share dealing activity. (No possible inducement).
- WPIC content is disseminated widely and made available to all interested parties through a range of different channels, therefore qualifying as a “Minor Non-Monetary Benefit” under MiFID II (ESMA/FCA/AMF). WPIC research is made freely available through the WPIC website. WPIC does not have any permissioning requirements on research aggregation platforms.
- WPIC does not, and will not seek, any payment from consumers of our research services. WPIC makes it clear to institutional investors that it does not seek payment from them for our freely available content.
More detailed information is available on the WPIC website:
https://www.platinuminvestment.com/investment-research/mifid-ii
Contacts:
Edward Sterck, Research, [email protected]
Wade Napier, Research, [email protected]
Brendan Clifford, Head of Institutional Distribution, [email protected]
WPIC does not provide investment advice.
Please see disclaimer for more information.